
U.S. Dollar Rebound: The Impact of Rising Rates and Government Debt


|
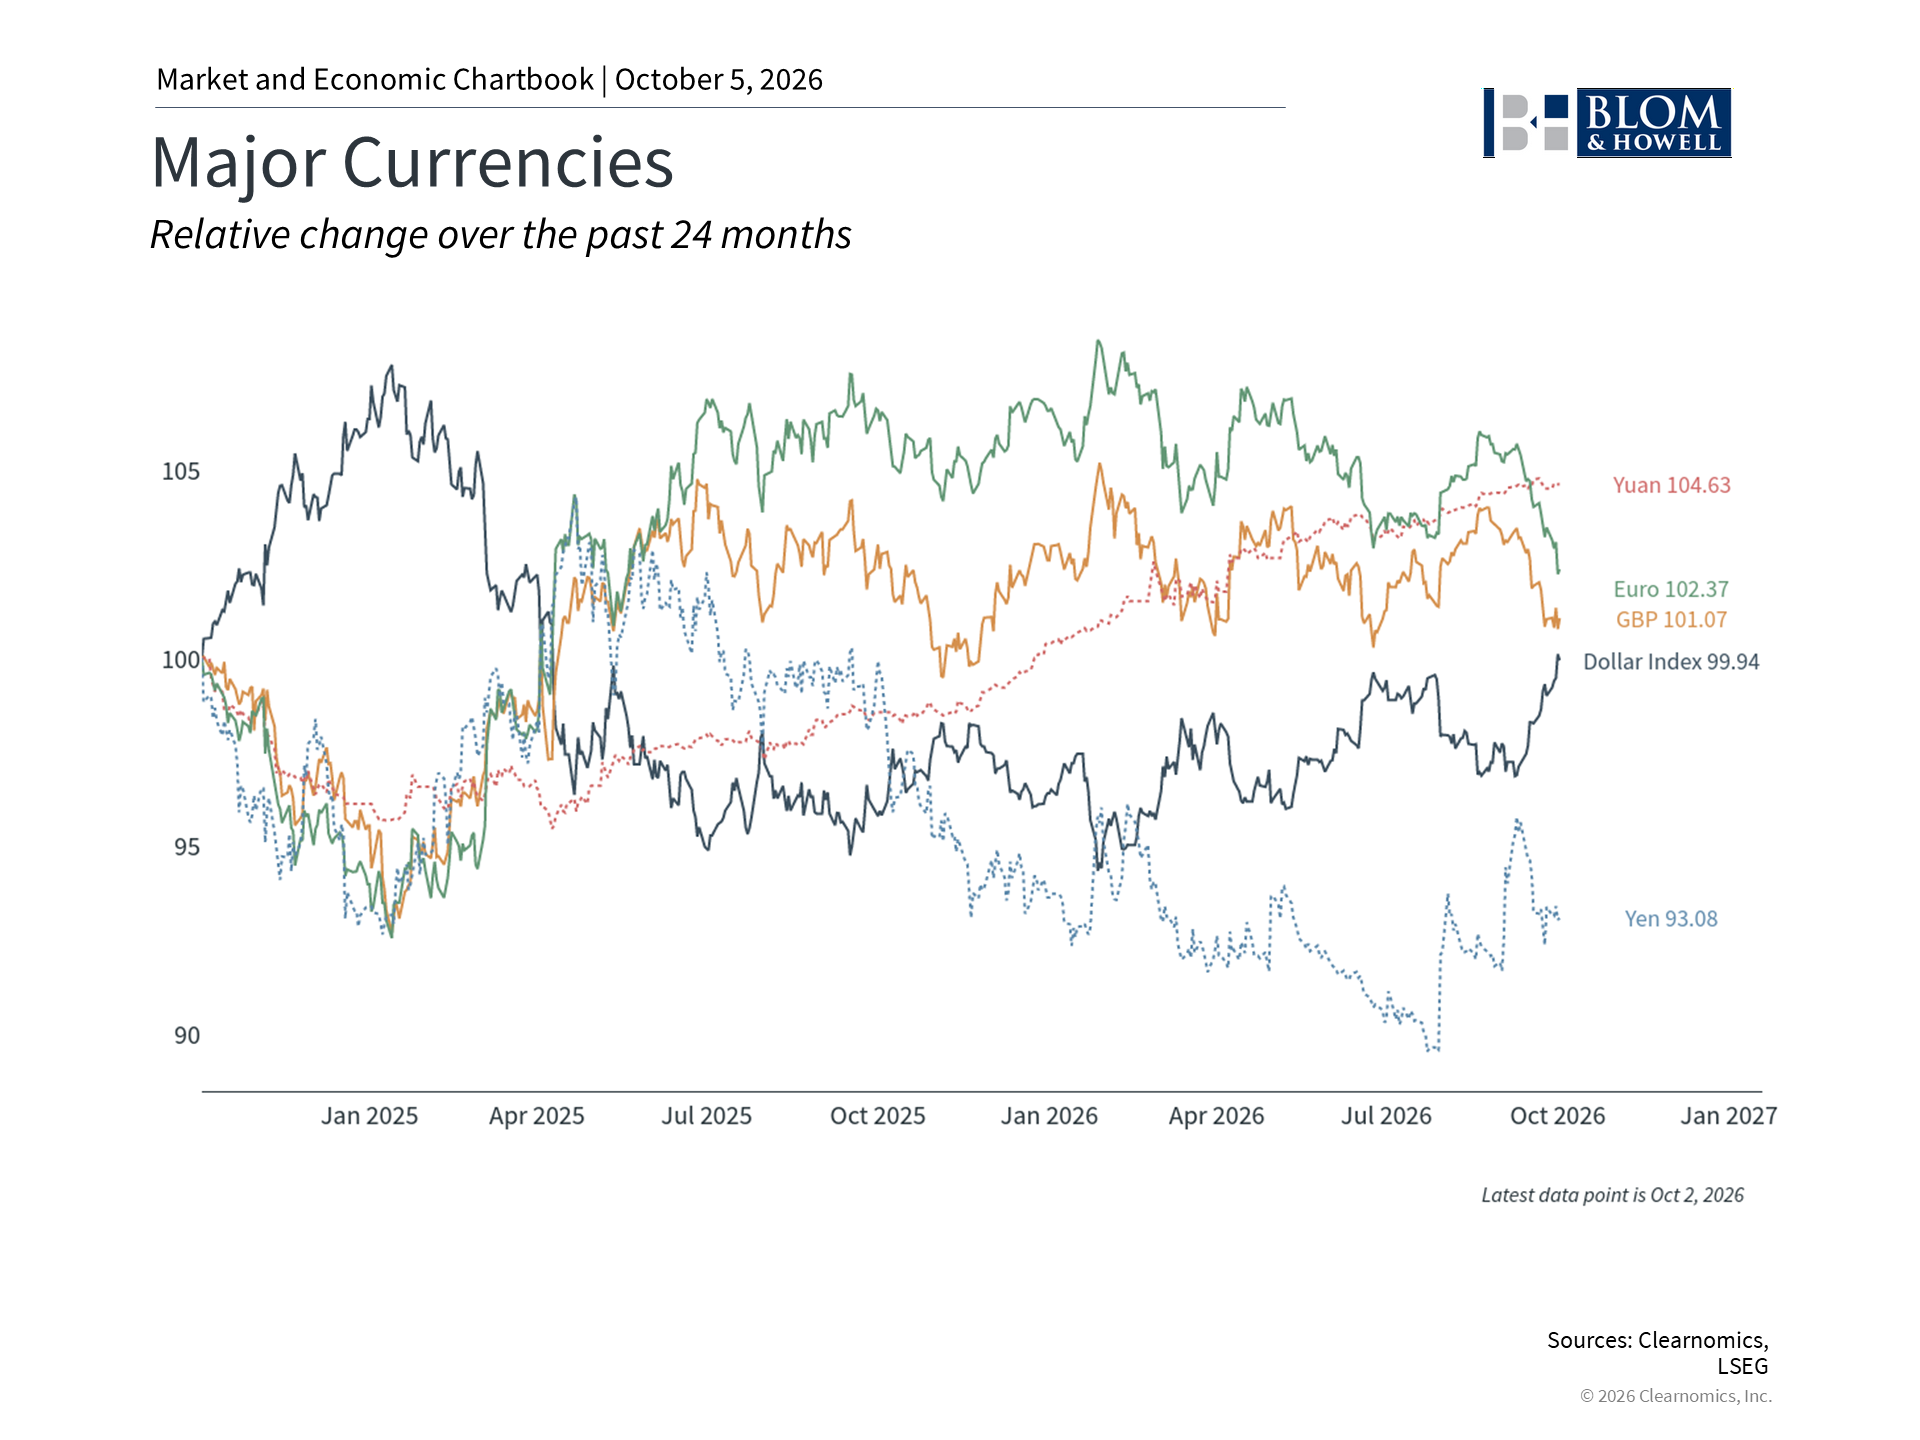
As interest rates have risen to multi-decade highs, one of the implications that has received less attention is the strengthening U.S. dollar. The dollar affects all aspects of financial markets, the economy, and everyday life. Its value impacts the cost of imported goods, foreign travel, the revenues of U.S. businesses that operate around the world, and portfolios with international assets. In addition, the dollar is affected by the outlook on U.S. economic growth, interest rates, and concerns around the national debt. In other words, many factors impacting global financial markets are reflected in the dollar. This is relevant for long-term investors because the dollar has recently recovered to its highest level since last year’s “Liberation Day” tariff announcements. This rebound has been broad, with the euro, British pound, and Japanese yen all weakening as the dollar has strengthened. Higher Treasury yields are one of the most important reasons for this, with long-term interest rates such as the 10-year and 30-year Treasury yields at over 20-year highs. These trends also reflect the Fed’s shift to hiking policy rates again, which naturally raises shorter-term yields.1 While a stronger dollar is beneficial in some ways, its overall effects can be more complex. For consumers, a stronger dollar does make it more affordable to import goods and travel internationally. However, it can also make U.S. exports less competitive for businesses. Additionally, a rising dollar can act as a headwind to the returns of international investments, just as a falling dollar can support them. So, what is driving the dollar's recent strength, and what does it mean for investors? The dollar has strengthened against major currencies
The dollar, as measured by the U.S. Dollar Index (DXY), which is based on a basket of six major foreign currencies, is now near 102 after hovering at or below 100 for the past year and a half. The chart above, which shows each currency’s value relative to its level two years ago, shows that the dollar is back to where it started after a period of weakness. Looking over a longer time horizon, current levels are among the strongest in nearly 25 years, with the exception of the peaks between 2022 to early 2025 when the index reached as high as 114.2 Why has the dollar rebounded? One important feature of global markets is that when interest rates in the U.S. rise against those in other countries, it makes U.S. bonds and other assets more attractive in relative terms. This idea is often referred to as the “carry trade.” In a simple version, traders borrow in currencies with low interest rates and invest these funds in higher-yielding assets, such as U.S. Treasuries. This dynamic means that capital may flow into dollar-denominated assets when yields are rising, thus supporting the dollar. This is especially relevant today because the rise in U.S. rates is not just due to inflation, but because real, inflation-adjusted rates have increased. This means that the "true" return investors earn after accounting for rising prices has improved, which makes these yields even more attractive relative to those of other countries and regions. That said, dollar movements are exceptionally difficult to predict, and they don’t always just follow interest rates. For example, the dollar might experience sudden strength in challenging times because it can serve as a safe-haven asset when investors seek stability. However, because the dollar reflects both broad economic and global dynamics, it can be volatile when these trends are uncertain, as they have been over the past several years. Global and fiscal concerns have led to dollar fluctuations
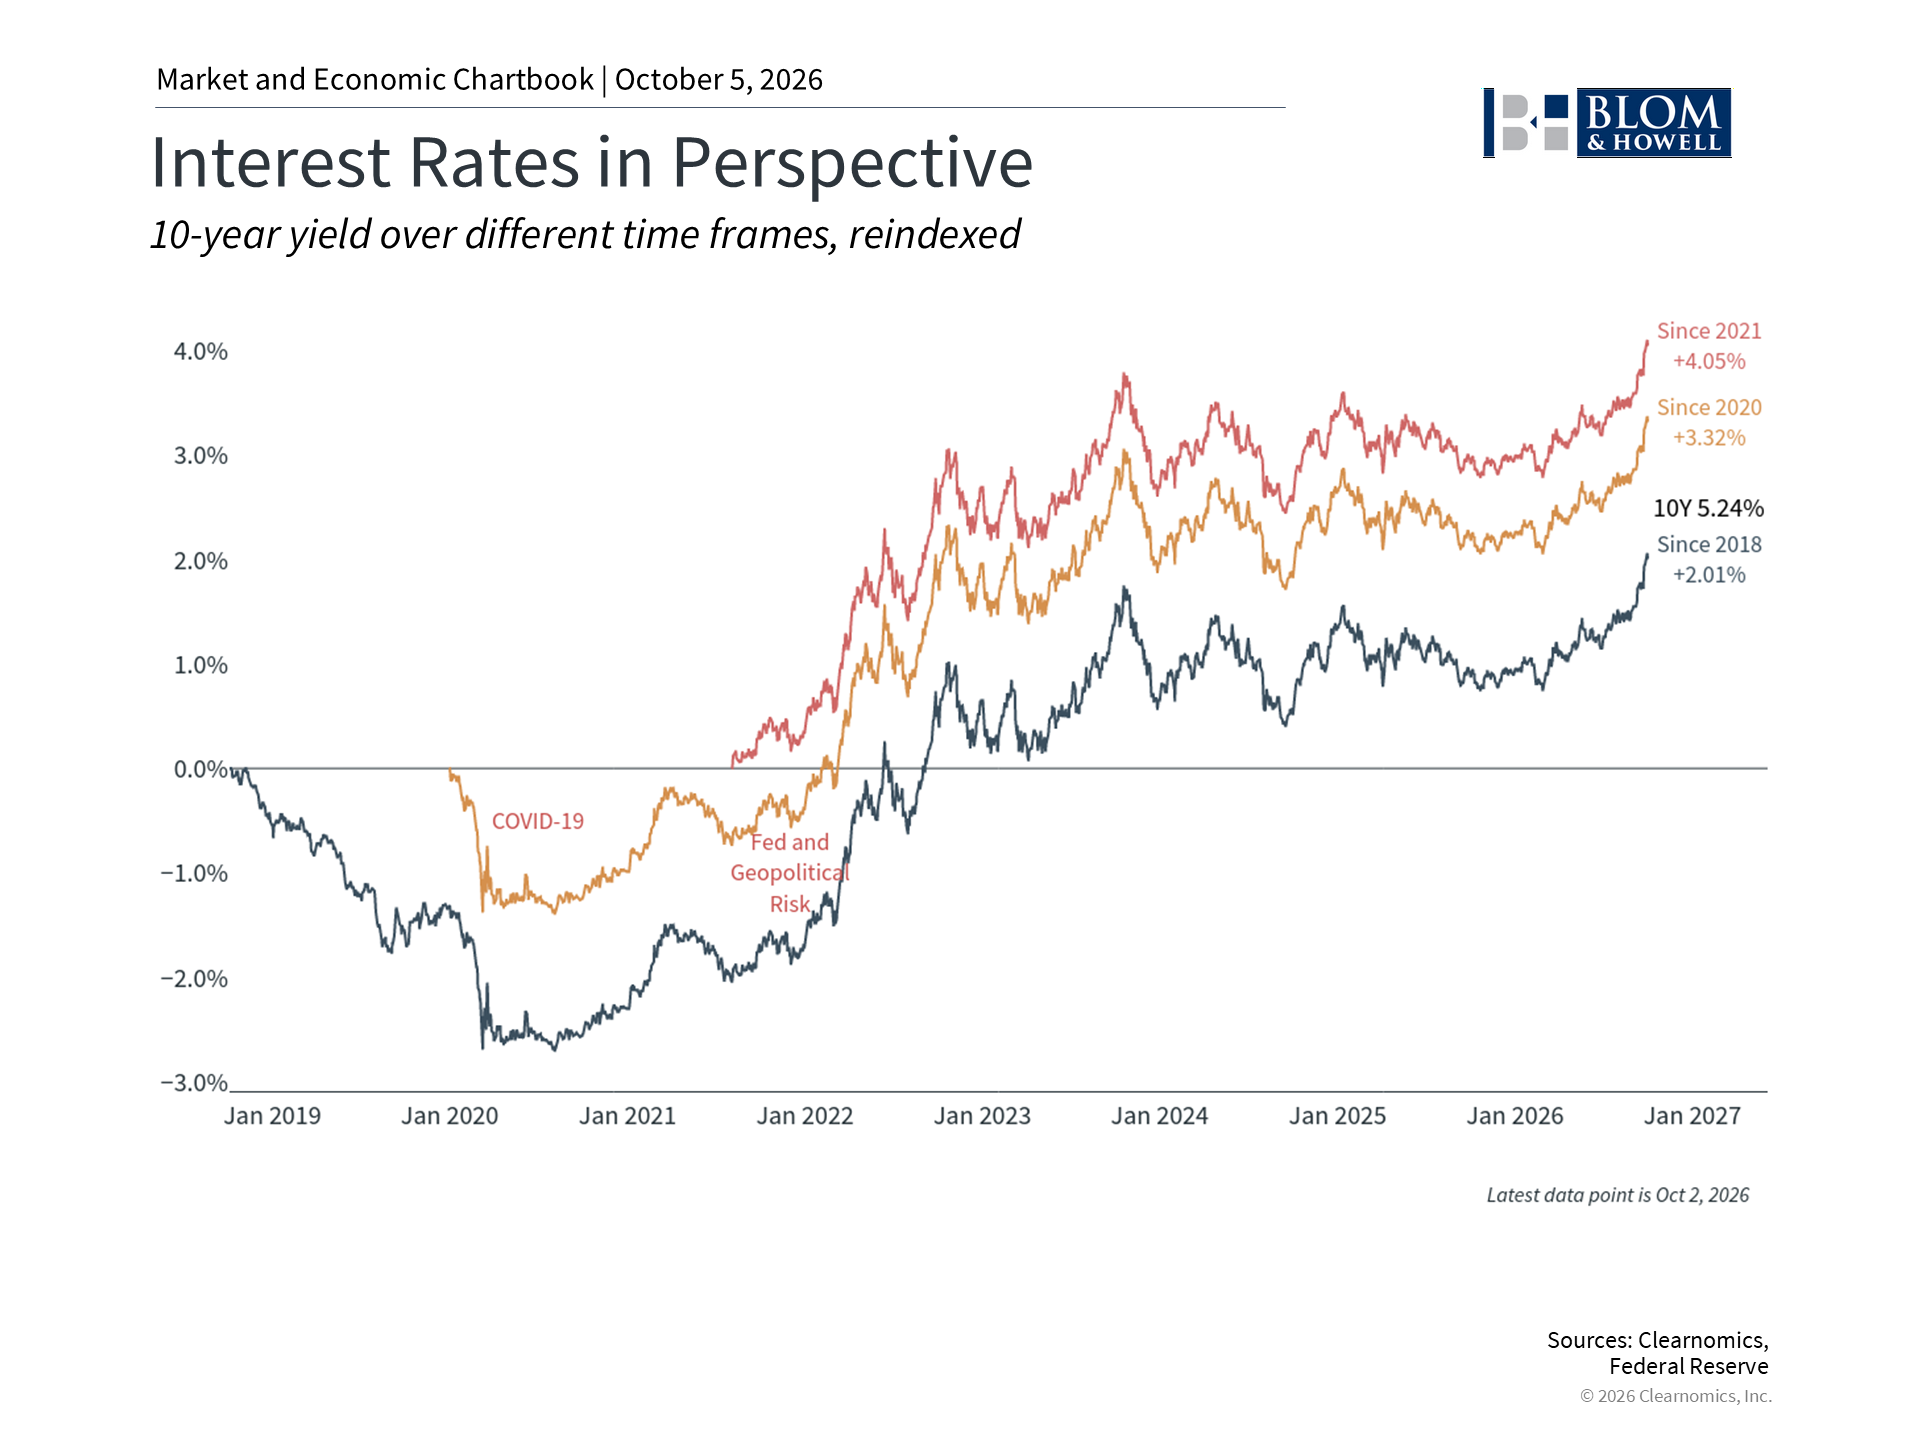
Another important aspect of the dollar and interest rates is the effect of the national debt and persistent federal budget deficits. Since higher debt levels can raise concerns over the ability and willingness of the government to pay back its obligations, this can naturally weaken the dollar. Rising interest rates, particularly the 10-year exceeding 5.3% and the 30-year around 5.7%, can worsen this situation because they raise the level of interest payments and make it more difficult for the government to roll over its debts, increasing the overall debt burden. In fact, part of the reason yields have risen may be due to concerns over the level of the debt and growing deficits. So, it’s interesting that the dollar has strengthened despite this, especially amid reports that global central banks have at times shifted away from the dollar as the global reserve currency in recent years.3 A common question is whether there is a "breaking point" at which the debt becomes unsustainable. The reality is that this is untested, with the typical example being Japan which has operated with debt-to-GDP ratios well above 200% for decades.4 Other examples include Europe, where sovereign debt crises among the so-called PIIGS (Portugal, Italy, Ireland, Greece, and Spain) occurred regularly during the 2010s, ultimately requiring bailouts. Perhaps the biggest challenge is that fiscal sustainability does not appear to be a central focus in Washington at the moment. Despite these issues, the reality is that the U.S. still often acts as the lender of last resort and is where other countries and investors turn when there are global challenges. For example, the U.S. Treasury Department recently intervened in the foreign exchange market for the first time since the late 1990s to help Japan defend its currency. From a portfolio perspective, history shows that focusing too heavily on deficits when making investment decisions would have often been counterproductive. This is because deficits tend to be largest during crises, which is often when stocks are the most attractively valued. For example, deficits surged during the recessions around 2009 and 2020, periods that were followed by strong market recoveries. Dollar fluctuations can affect international asset returns
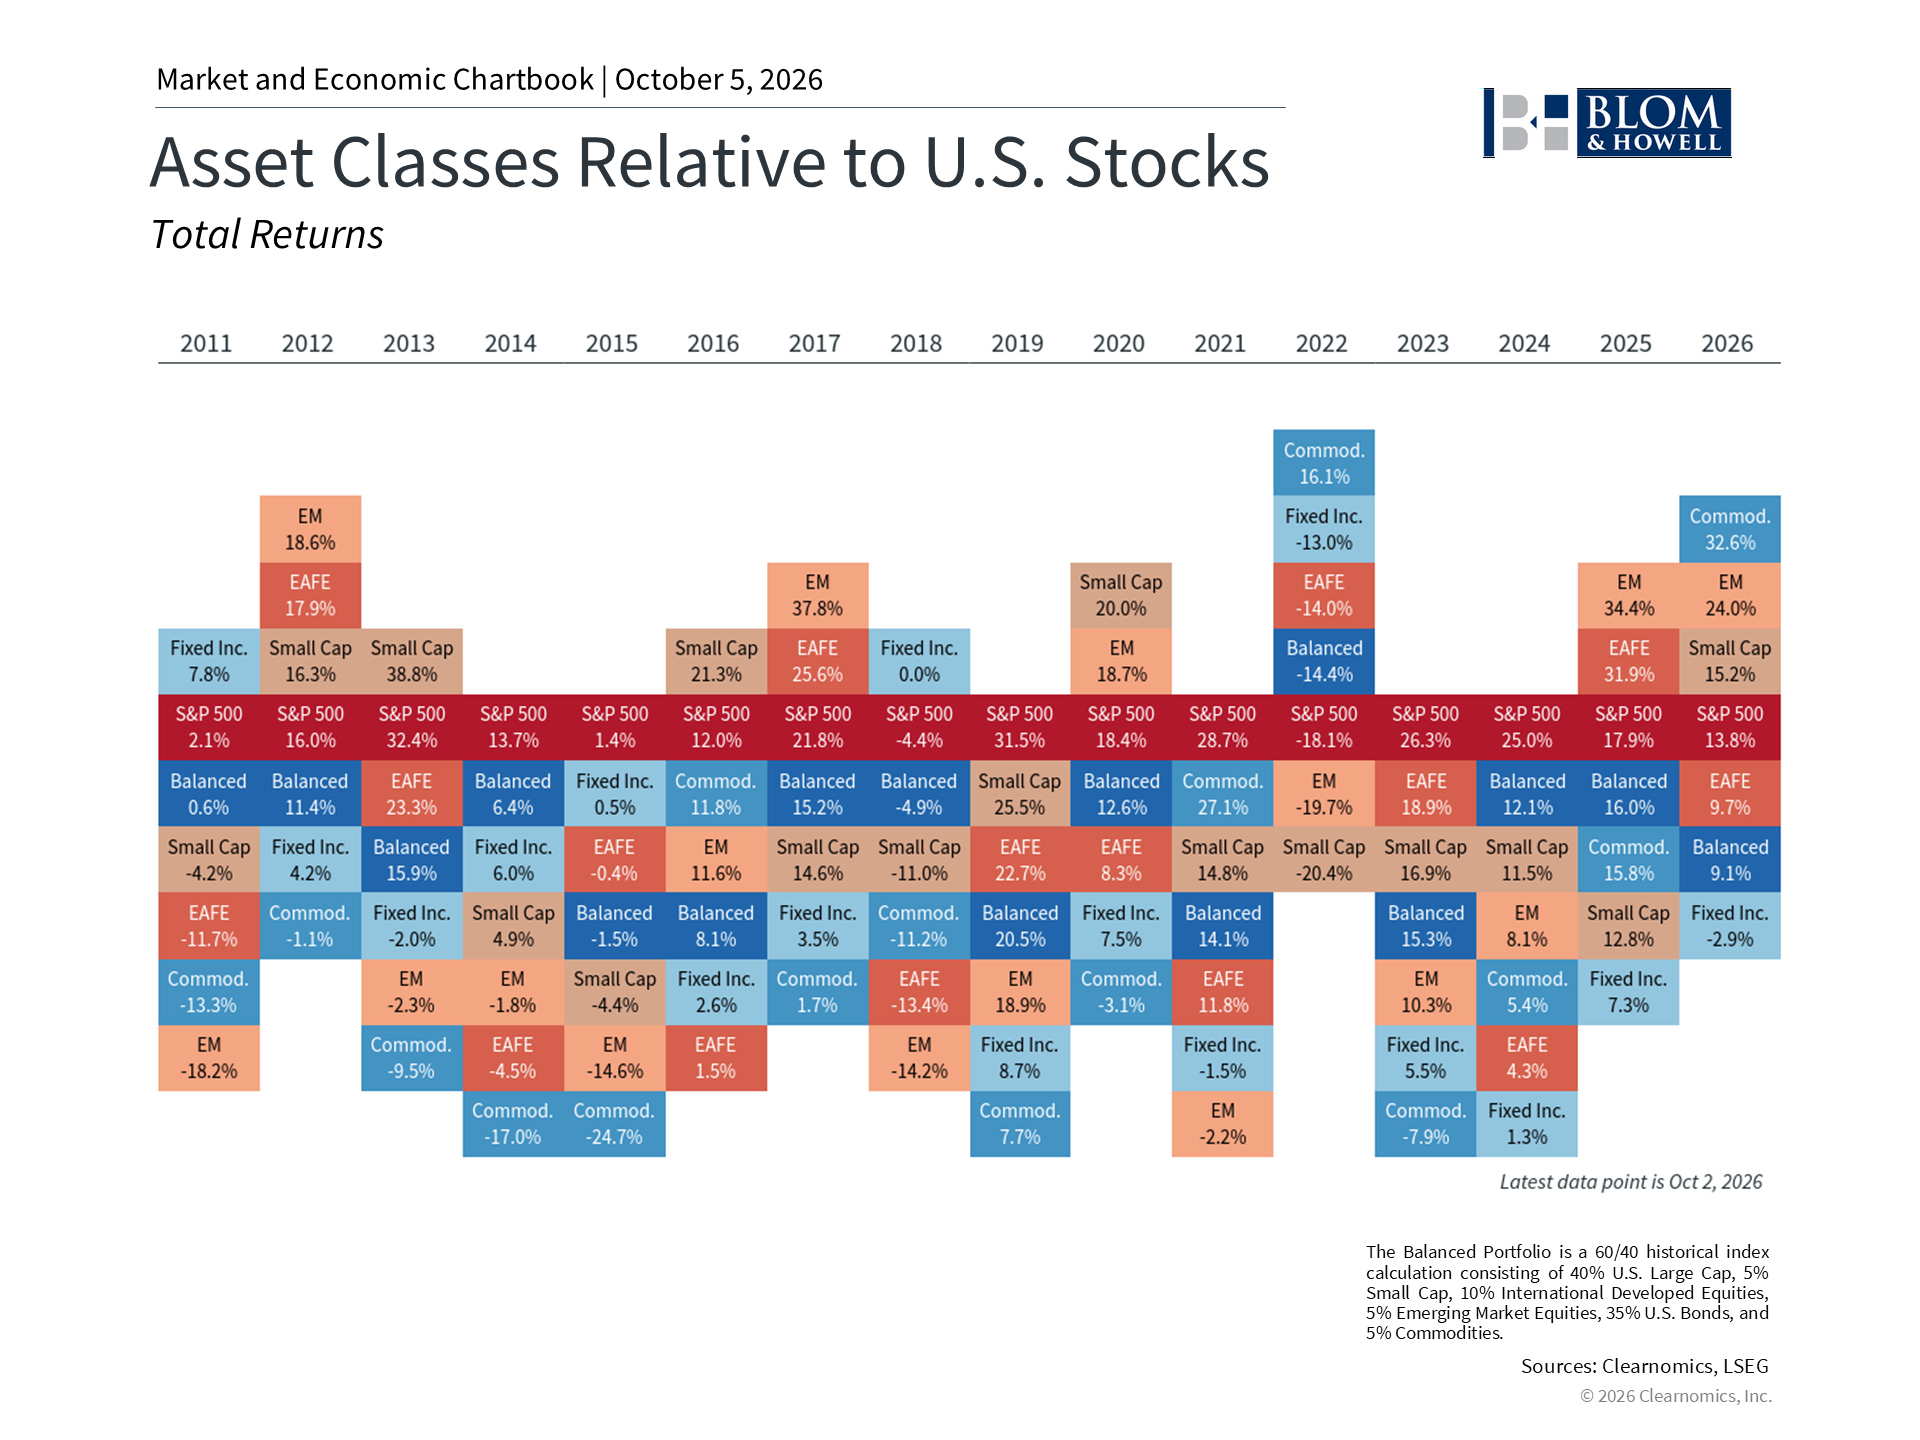
When it comes to portfolios, this discussion matters because dollar movements can be a key component of international returns. When U.S.-based investors own foreign stocks and bonds, those investments are made in local currencies that must eventually be converted back to dollars. When the dollar weakens, these foreign investments are worth more in dollar terms, which boosts returns, and vice versa. The same principle applies to U.S.-based businesses that export to international customers, since a weaker dollar means U.S.-made goods are more affordable for these buyers. This acted as a tailwind for diversified portfolios last year, when a weaker dollar helped support developed and emerging market returns. As the dollar has strengthened this year, this effect has reversed. For example, while emerging markets underperformed in the third quarter, they remain among the best performing asset classes so far this year.5 At the same time, currency movements are only one part of the picture. Fundamentals, including earnings and valuations, remain supportive across both developed and emerging markets, which has helped support the case for balanced portfolios. For example, the MSCI EAFE Index of developed market stocks and the MSCI EM Index of emerging market stocks currently have forward price-to-earnings ratios of 14.9x and 9.9x, respectively, compared to 19.2x for the S&P 500.6 Importantly, the dollar still remains the world's dominant reserve currency. Concerns about whether this will continue to be the case are not new, and similar questions arose during Japan's rise in the 1980s, after the introduction of the euro, amid China's economic expansion, and more recently with the growth of digital currencies. In each case, the dollar retained its central role, although with shifts in assets held by global institutions. The broader point for long-term investors is that currency movements are one of the many factors that affect portfolio returns. These movements can shift quickly in response to changes in interest rates, geopolitics, and economic expectations, as the past two years have shown. Rather than reacting to these swings, holding a balanced mix of domestic and international assets that are aligned with long-term goals is the best way to manage them. The bottom line? The dollar has strengthened over the past year due to higher real interest rates and its role as a safe-haven asset, despite fiscal concerns. Investors should continue to stay balanced across regions as global trends impact the dollar and other currencies. References 1. https://home.treasury.gov/policy-issues/financing-the-government/interest-rate-statistics 2. Clearnomics research using LSEG data, as of October 2, 2026 3. https://data.imf.org/en/datasets/IMF.STA:COFER 4. https://fiscaldata.treasury.gov/americas-finance-guide/national-debt/ 5. Clearnomics research using MSCI data, as of October 2, 2026 6. Clearnomics research using LSEG data, as of October 2, 2026 Index Descriptions S&P 500 The Standard & Poor’s 500 Index is a capitalization-weighted index of 500 stocks designed to measure performance of the broad domestic economy through changes in the aggregate market value of 500 stocks representing all major industries. MSCI Emerging Markets Index The MSCI EM (Emerging Markets) Index is a free float-adjusted market capitalization weighted index that is designed to measure the equity market performance of the emerging market countries of the Americas, Europe, the Middle East, Africa and Asia. The MSCI EM Index consists of the following emerging market country indices: Brazil, Chile, Colombia, Mexico, Peru, Czech Republic, Egypt, Greece, Hungary, Poland, Qatar, Russia, South Africa, Turkey, United Arab Emirates, China, India, Indonesia, Korea, Malaysia, Philippines, Taiwan, and Thailand. MSCI EAFE Index The MSCI EAFE Index is a free float-adjusted market capitalization index that is designed to measure the equity market performance of developed markets, excluding the U.S. & Canada. The MSCI EAFE Index consists of the following developed country indices: Australia, Austria, Belgium, Denmark, Finland, France, Germany, Hong Kong, Ireland, Israel, Italy, Japan, the Netherlands, New Zealand, Norway, Portugal, Singapore, Spain, Sweden, Switzerland and the UK. Bloomberg U.S. Aggregate Bond Index The Bloomberg U.S. Aggregate Bond Index is an index of the U.S. investment-grade fixed-rate bond market, including both government and corporate bonds. DXY The DXY is a U.S. dollar index based on a basket of currencies, including the Euro, Yen, Pound, Canadian Dollar, Swedish Krona and Swiss Franc. |
|||
|
Investment advisory services are provided by Blom & Howell Financial Planning, Inc. Copyright (c) 2026 Clearnomics, Inc. All rights reserved. The information contained herein has been obtained from sources believed to be reliable, but is not necessarily complete and its accuracy cannot be guaranteed. No representation or warranty, express or implied, is made as to the fairness, accuracy, completeness, or correctness of the information and opinions contained herein. The views and the other information provided are subject to change without notice. All reports posted on or via www.clearnomics.com or any affiliated websites, applications, or services are issued without regard to the specific investment objectives, financial situation, or particular needs of any specific recipient and are not to be construed as a solicitation or an offer to buy or sell any securities or related financial instruments. Past performance is not necessarily a guide to future results. Company fundamentals and earnings may be mentioned occasionally, but should not be construed as a recommendation to buy, sell, or hold the company's stock. Predictions, forecasts, and estimates for any and all markets should not be construed as recommendations to buy, sell, or hold any security--including mutual funds, futures contracts, and exchange traded funds, or any similar instruments. The text, images, and other materials contained or displayed in this report are proprietary to Clearnomics, Inc. and constitute valuable intellectual property. All unauthorized reproduction or other use of material from Clearnomics, Inc. shall be deemed willful infringement(s) of this copyright and other proprietary and intellectual property rights, including but not limited to, rights of privacy. Clearnomics, Inc. expressly reserves all rights in connection with its intellectual property, including without limitation the right to block the transfer of its products and services and/or to track usage thereof, through electronic tracking technology, and all other lawful means, now known or hereafter devised. Clearnomics, Inc. reserves the right, without further notice, to pursue to the fullest extent allowed by the law any and all criminal and civil remedies for the violation of its rights.

|
Posts you may like

What’s Driving Portfolios: The Impact of High Oil and Copper Prices


